
Choosing housing in Canada means comparing provinces, cities, neighbourhoods and property types—not just national house-price headlines. Renting rules vary across provinces and territories, and the costs of owning a condominium differ from those of a detached house. This guide gives newcomers and existing residents a decision framework grounded in official Canadian housing guidance.
Should you rent or buy in Canada?
Renting generally requires less money upfront and may be useful while exploring a new city, changing jobs or learning the local market. Buying can provide longer-term control, but comes with a down payment, transaction costs, mortgage obligations and ongoing maintenance. The Canada Mortgage and Housing Corporation (CMHC) publishes resources for newcomers that cover both options.
- Renting costs: contract rent, permitted deposits, utilities, insurance, parking, transport, moving costs and any building-specific fees.
- Buying costs: down payment, mortgage payments, property tax, utilities, insurance, legal fees, inspections, closing expenses and condo fees if relevant.
- Living costs: heating needs, commuting, childcare, parking and the ability to maintain an emergency fund.
Renting: provincial rules and practical checks
Canada does not have one national residential lease law governing every rental. Rules for deposits, rent increases, ending a tenancy, repairs and dispute resolution depend on the province or territory and sometimes the type of housing.
The Financial Consumer Agency of Canada’s rental guide explains why rent alone is not a complete budget. It also recommends reviewing your financial situation before committing.
Before paying a deposit, identify the official tenancy regulator for the property, confirm the landlord or authorised representative, inspect the property and check whether the agreement states who pays utilities and how maintenance requests are handled. Document the unit’s condition at move-in and keep signed copies and payment records.
Avoid rental scams and misleading listings
Be cautious if someone will not allow a reasonable property viewing or independent verification, pressures you to transfer money unusually quickly, or cannot establish their right to rent the unit. Confirm the address, contract, building rules and permitted payment process before sending funds. A polished listing does not establish that the person offering it is authorised to lease the property.
Buying a home: financing and ongoing expenses
The Financial Consumer Agency of Canada homebuying guide describes budgeting, mortgage shopping and upfront closing costs. Obtain information from lenders for your circumstances; qualification, available products and insurance requirements may vary.
Look beyond a listing price or an estimated mortgage payment. Ask for costs associated with inspection, legal work, title or registration, property-tax adjustments, moving, insurance, repairs and the specific province’s land-transfer or property-transfer rules. For a condominium, review condo documents, regular fees, reserve-fund information and potential special assessments.
Non-Canadian purchasers should also verify current federal and provincial ownership eligibility before entering a binding agreement. Rules can be time-limited and exception-based; do not assume a property may be purchased simply because it is publicly advertised.
Three affluent residential locations to research
If you are moving to a Canadian city for the first time, create two lists: what you need from the actual home and what you need from its surroundings. A condominium may offer easier building maintenance but comes with building-specific rules and monthly fees; a detached property may provide outdoor space while placing greater responsibility for repairs, insulation, landscaping and winter upkeep on the owner. Rental protections and purchase taxes are provincial, so compare the right legal framework before comparing prices.
Affluent Areas’ initial Canadian coverage will examine Yorkville, West Vancouver and Westmount. They involve different cities, housing patterns and daily routines. They are not direct substitutes for every household, and the presence of expensive properties does not prove that one location is objectively best.
Yorkville, Toronto
Start with apartment and condominium availability, walkability, transit connections, building amenities and fees. Compare the specific street and tower, as noise, maintenance obligations and unit sizes can differ even within the same small area. For a family, verify school arrangements and living space before prioritising centrality.
West Vancouver, British Columbia
Analyse residential neighbourhoods individually rather than treating the entire municipality as one market. Consider hillside access, commuting over regional crossings, detached-home maintenance, school travel and the exact property’s natural-hazard and insurance considerations. Check relevant municipal and provincial sources for the address.
Westmount, Montreal area
This municipality requires a different decision framework from downtown Toronto or coastal British Columbia. Consider detached houses versus apartments, local transport, heating and maintenance needs, municipal rules and practical French-language requirements in daily administration where applicable. Verify which services and schools actually serve the property.
Transit and address-level checks in the three communities
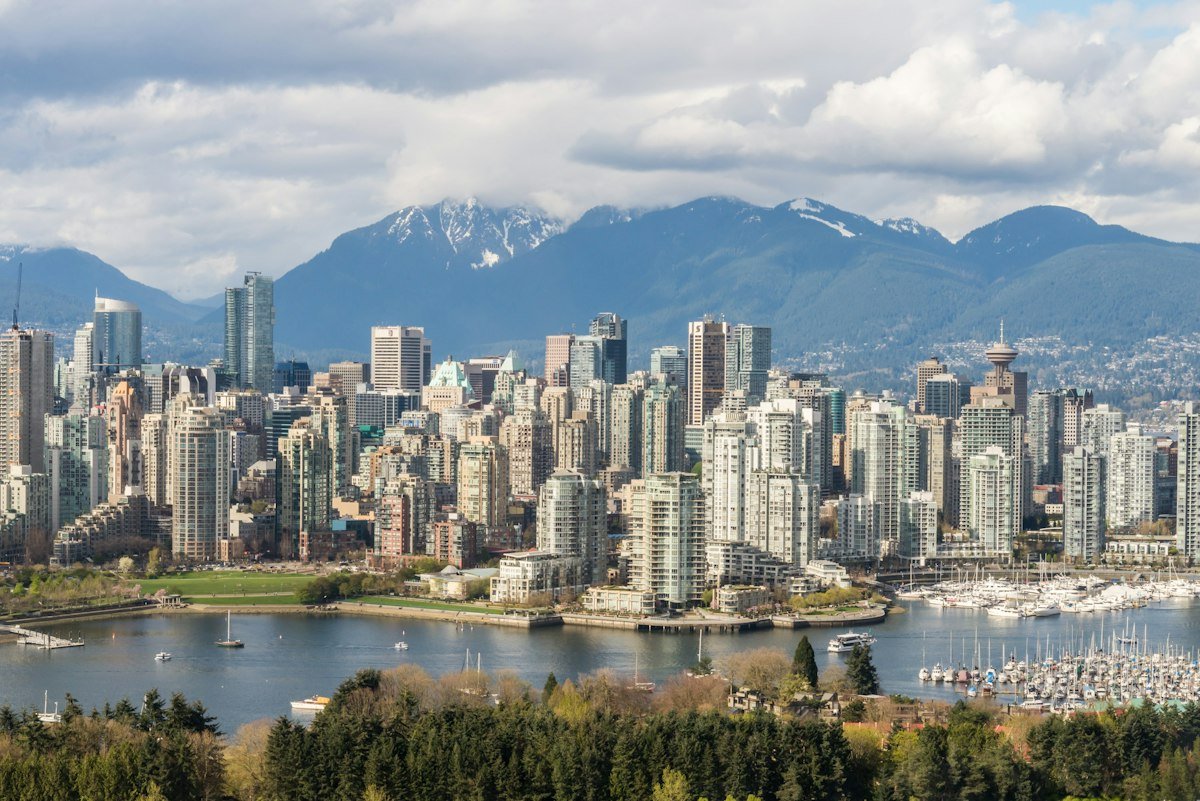
To compare Toronto and West Vancouver, do not simply compare their metropolitan maps. Yorkville is a central Toronto neighbourhood, whereas West Vancouver contains distinct residential locations with different access to transit and regional crossings. In Montréal’s Westmount, the day-to-day balance may involve different transport links and municipal services. Review Toronto Transit Commission, Metro Vancouver TransLink, and Montréal’s STM for current journey information. Measure door-to-door time for the individual property.
For buyers, property-tax bills, building reserves, heating costs and prospective repairs can be as important as the purchase price. For renters, ask exactly what utilities or parking the advertised rent covers. In either case, look at evidence for the specific dwelling rather than taking a neighbourhood average as an estimate for your household.
How to compare Canadian neighbourhoods
- Choose two or three communities based on work locations, household needs and transport.
- Gather comparable current rentals or sold-property evidence using the same dwelling type and timeframe.
- Calculate year-round housing and commuting costs, including winter utilities and maintenance.
- Check education, healthcare and accessibility from official local sources instead of using general marketing claims.
- Understand the housing contract, condo documents or ownership rules for each property.
- Visit the neighbourhood at different hours, including the route to essential amenities.
Questions before signing or purchasing
- Which provincial or territorial tenancy and ownership rules apply?
- Does the advertised unit belong to the building, owner and address represented?
- What happens if the rent, mortgage rate or building fees change?
- What are the insurance and maintenance obligations?
- Have I checked property boundaries, building rules, commute, parking and accessibility?
- For a purchase, have I reviewed financing terms and received suitable independent advice?
More Canada resources
Explore our living in Canada guides, moving to Canada guides and education in Canada guides while planning a relocation and neighbourhood shortlist.
Official references
- CMHC: housing for newcomers.
- Financial Consumer Agency of Canada: renting a home.
- Financial Consumer Agency of Canada: buying a home.
Reviewed 17 October 2026. Provincial rules, housing costs, mortgage requirements and foreign-buyer eligibility change; confirm the latest details for the specific property. This is general housing information, not legal, tax or mortgage advice.