
Housing in the United States is a local decision shaped by state law, county and city costs, and neighbourhood characteristics. A property in New York City will have different building arrangements and ownership questions from a home in Miami or Los Angeles. This guide helps you compare renting and buying, understand costs beyond a listing price and make a more useful neighbourhood shortlist.
Renting vs buying a home in the United States
Renting can suit people who need flexibility, have not explored the area or are unsure how long they will stay. Buying can offer control and longer-term occupancy, but requires more money upfront and makes you responsible for a wider range of expenses. Compare both options for your own timeline rather than assuming one always builds more wealth.
- Renting: plan for rent, applicable deposit and application costs, utilities, renters insurance, parking, transport and moving expenses.
- Owning: consider down payment, mortgage principal and interest, property taxes, homeowners insurance, maintenance, closing costs and any homeowner association or condominium charges.
The Consumer Financial Protection Bureau provides a step-by-step guide for homebuyers. Its Loan Estimate explainer helps borrowers compare mortgage offers using costs and terms, not a quoted interest rate alone.
Rental protections depend on where the property is
Tenancy and landlord-tenant requirements vary by state and locality. Before signing a lease, confirm applicable rules on application screening, security deposits, notices, rent changes, maintenance and termination. USAGov’s tenant-rights directory helps identify the relevant state resources if problems arise.
Federal fair-housing protections also apply to discrimination in many residential housing activities. The exact property, circumstances and applicable law still matter. Keep written records, inspect the unit before move-in, photograph existing damage and clarify who pays for utilities, repairs, parking and amenities.
Buying a US property: look beyond the down payment
The advertised sale price is only the starting point. Mortgage applicants should request and compare formal Loan Estimates and examine the Closing Disclosure before completing a purchase. Check taxes and insurance for the address; two properties with similar prices can have quite different carrying costs.
Ask about property-condition inspections, title and ownership, flood or other insurance considerations, community rules and any pending assessments or major building work. For a condominium, obtain the association documents and financial information. For a cooperative apartment, review the ownership arrangement, board procedures and occupancy restrictions with qualified advisers.
Choosing where to live: three different US location examples
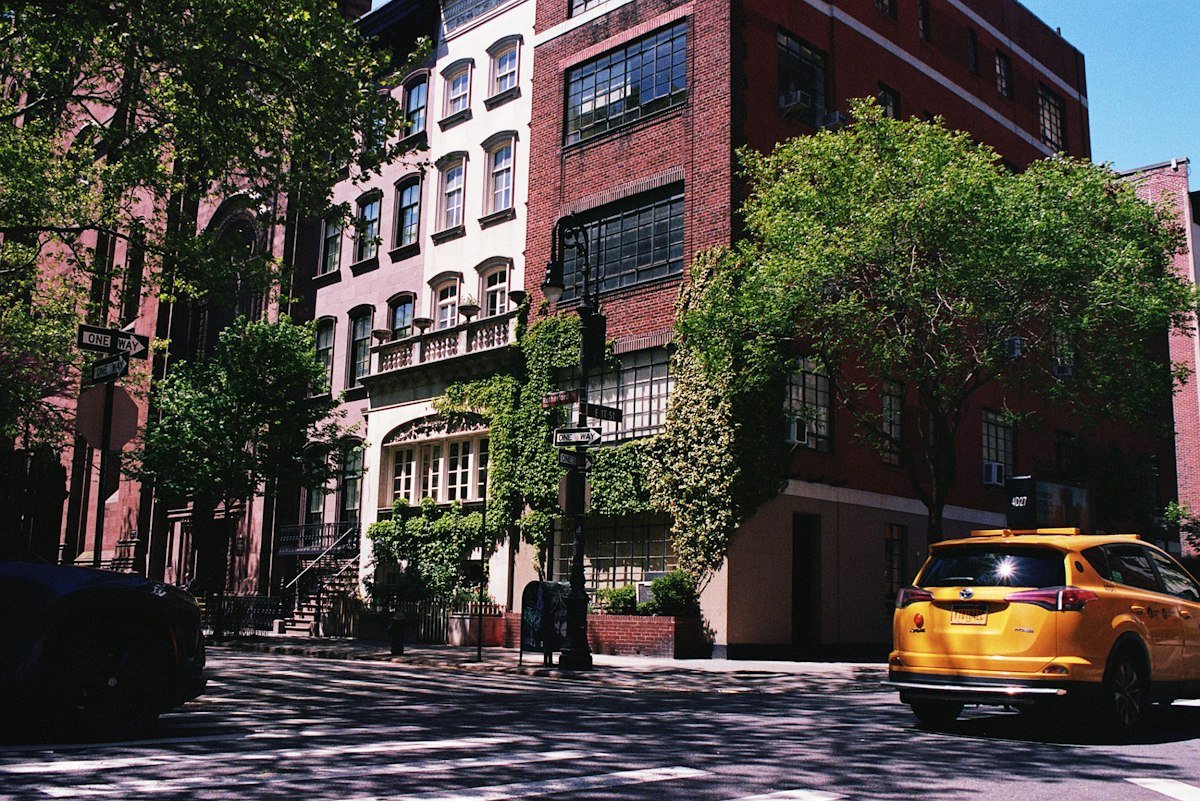
Even within one city, a neighbourhood label can conceal major differences in the types of property on offer. In New York, it pays to distinguish condominium units, cooperative apartments and rented apartments, because the approval process, ownership structure and common charges differ. In the Miami area, island access or building-level assessments may affect the practical budget. In and around Beverly Hills, it is essential to check the actual municipal boundary rather than relying on a real-estate listing’s marketing label. The best starting point is always an address-specific comparison.
Affluent Areas is preparing deeper research on three areas with quite different housing markets. Each is a research example rather than a recommendation to buy or a claim about future appreciation.
Upper East Side, New York City
Compare building types, condominium versus cooperative ownership, proximity to subway services, access to parks and the difference between major avenues and quieter side streets. Investigate building-specific monthly charges, entrance accessibility, noise, and possible alteration rules. A single neighbourhood label covers very different everyday experiences.
Fisher Island, Miami area
This is a distinctive island residential market where transport logistics, property access and building-level costs deserve extra attention. Before considering an address, investigate the actual route to the mainland, visitor and service access, flood and insurance exposure, property-association requirements and recurring charges. Do not infer cost or suitability from luxury branding.
Beverly Hills, Los Angeles area
Verify whether a property lies within the incorporated City of Beverly Hills or a nearby area marketed using a Beverly Hills postal address. Compare the actual jurisdiction, public services, property-tax record, hillside or building-maintenance factors, car travel times and neighbourhood character. Geographic precision matters for practical decisions.

What to check in a high-value housing market
A household choosing between a Manhattan apartment and a California home may be considering lifestyle as much as budget. Compare private space, building amenities, parking, accessibility and how often you will need a car. A larger property may mean more responsibility for maintenance, insurance and outdoor space; a managed apartment building may have shared charges, board rules and planned works. Do not assume either is better without seeing those costs in writing.
Search-result headlines about “the most expensive neighbourhood” are not a substitute for a housing budget. Assess the exact property-tax jurisdiction, insurance quote, condition, commute and any flood or wildfire information from relevant local authorities. For school-dependent moves, check school boundaries and enrolment directly rather than assuming that a desirable postcode guarantees a place.
A location-comparison framework
- Define the job: moving permanently, renting temporarily, raising a family, downsizing or investing each leads to a different shortlist.
- Calculate total housing costs: obtain property-specific prices and dated tax, fee and insurance estimates.
- Test transport: calculate journeys to work, school, airports and routine services at the times you use them.
- Compare housing stock: check age, construction type, condition, maintenance history and common-area responsibility.
- Validate neighbourhood claims: investigate amenities and public data without assuming high home values mean low crime or better schools.
- Inspect and verify: visit the precise block or building, not just the general neighbourhood.
Questions to ask before committing
- Is the address in the municipality and school district I think it is?
- Are property taxes, building charges, utilities and insurance included in my estimate?
- What lease, board or association rules restrict how the property can be used?
- Have I independently checked the commute, parking and accessibility?
- Are there foreseeable repairs, assessments, flood risks or other costs?
- Do I have the legal and financial advice needed for this transaction?
Continue researching the US
See our United States living guides, moving to the United States guides and US education guides. Individual neighbourhood comparisons should use current local sources rather than generic national averages.
Official sources
- CFPB: buying a house and comparing mortgage Loan Estimates.
- USAGov: tenant rights and state resources.
- HUD: fair-housing rights.
Reviewed 17 October 2026. Housing law, fees and market conditions differ by state and locality and change over time. This is general location research, not property, legal, tax or mortgage advice.